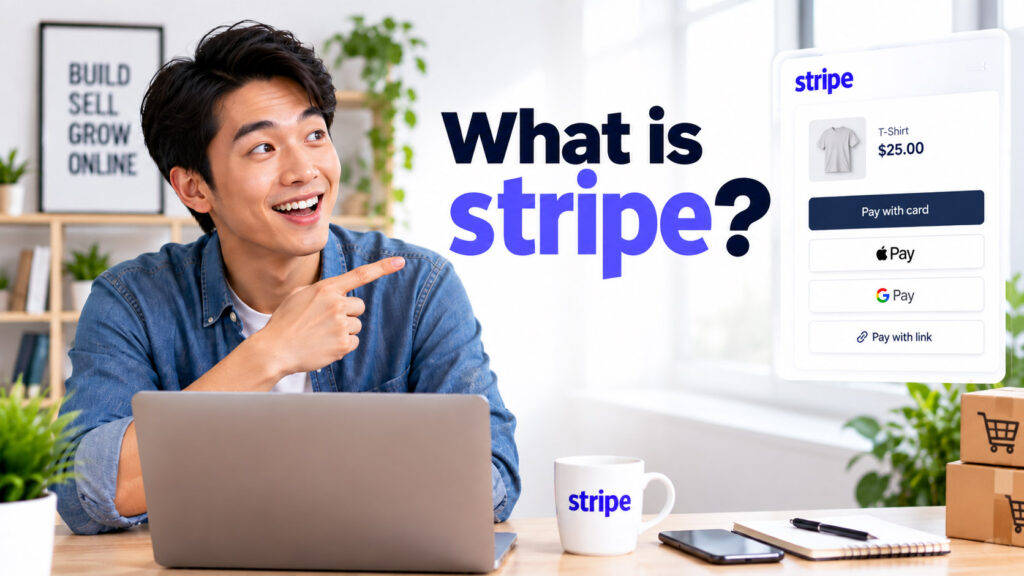
Stripe is a financial infrastructure and payments technology platform used by businesses to accept and manage money online and in person. But Stripe is much more than the technology behind a credit card form or checkout page.
In this beginner-friendly guide, you’ll learn how Stripe works, how online payments are processed, which Stripe products businesses can use, how subscriptions and recurring payments work, and what to consider when it comes to security, fees, international payments, marketplaces, and donations.
1. What Exactly Is Stripe?
Stripe is a technology company that provides programmable financial infrastructure. Its best-known service is payment processing: businesses can integrate Stripe into websites, applications, checkout pages, and other payment experiences so customers can pay online.
During a transaction, several parties may be involved, including the customer, merchant, banks, card networks, digital wallets, and other payment providers. Stripe provides software and infrastructure that helps transmit payment information, request authorization, record transaction results, manage follow-up events, and support settlement and payouts.
Stripe provides the infrastructure businesses need to collect payments and build payment-related workflows without creating the underlying banking and card-network infrastructure themselves.
2. Why Do Businesses Use Payment Platforms Like Stripe?
Accepting payments online is considerably more complex than adding a credit card number field to a website.
A modern payment system may need to handle:
- Sensitive payment information
- Payment authorization
- Customer authentication
- Failed payments
- Refunds and disputes
- Fraud prevention
- Different currencies
- Local payment methods
- Recurring billing
- Regulatory and compliance requirements
Instead of building this infrastructure independently, businesses can integrate a payment platform. This can provide a faster route to launching an online checkout while still giving developers significant control over the customer experience and underlying business logic.
3. How Does a Stripe Online Payment Work?
Although payment processing involves complex financial infrastructure behind the scenes, the customer-facing process can be summarized in a few steps.
Customer chooses what to pay for
The customer selects a product, service, membership, subscription, or donation amount.
Checkout collects transaction information
The payment experience collects the information required to process the transaction.
Payment details are submitted securely
Payment information is transmitted through the payment integration.
Authorization is requested
The payment request travels through the relevant financial networks for authorization.
The payment receives a result
The payment may be approved, declined, or require an additional authentication step.
The website receives confirmation
The website or application receives the payment result and displays an appropriate confirmation or error message.
Funds become eligible for payout
After processing and settlement, eligible funds can become available for payout according to the Stripe account’s payout schedule.
Important: This is a simplified example. The exact payment flow depends on factors such as the payment method, country, currency, authentication requirements, and integration configuration.
4. What Is Stripe Payments?
Stripe Payments is Stripe’s core payments product. It is designed for businesses that need to accept payments online, in person, or across different markets.
Stripe’s public materials describe support for more than 125 payment methods through its payments platform, although actual availability depends on factors such as the business location and transaction context.
Payment options can include:
- Credit and debit cards
- Digital wallets
- Bank-based payment methods
- Buy-now-pay-later methods
- Region-specific payment options
Businesses should choose payment methods based on their customers and business model rather than simply enabling every available option.
5. Stripe Checkout vs. Elements vs. Payment Links
Stripe provides several approaches for creating the customer-facing payment experience.
Stripe Checkout
A prebuilt checkout experience designed to reduce the amount of payment interface development a business needs to create from scratch. It can be used for one-time and subscription-related payment flows.
Stripe Elements
Embeddable user-interface components that give developers more control over how payment forms appear and behave inside a website or application.
Stripe Payment Links
Shareable payment pages that can be useful when a complete custom checkout is unnecessary.
The right option depends on the project. A business that prioritizes speed may prefer a prebuilt payment experience, while a software platform requiring a highly customized checkout may need a deeper integration.
6. One-Time Payments vs. Recurring Payments
One-time and recurring payments may look similar to customers, but they represent different payment models.
One-Time Payments
A customer is charged for a single transaction.
- Buying a product
- Paying an invoice
- Booking a service
- Making a one-time donation
Recurring Payments
The payment relationship continues over time.
- Software subscriptions
- Memberships
- Retainers
- Ongoing services
- Recurring donations
Recurring billing introduces additional requirements such as renewal schedules, payment-method updates, failed-payment handling, cancellation logic, trials, upgrades, downgrades, and customer communication.
Stripe Billing is designed around these subscription and recurring-revenue workflows.
7. What Payment Methods Does Stripe Support?
Stripe supports a broad range of payment methods, but availability varies depending on the country, business, currency, and individual Stripe account.
Examples described in Stripe documentation include:
Businesses should always verify payment-method availability for their own Stripe account and target markets rather than assuming every payment method is universally available.
8. Is Stripe Secure? Security and PCI Compliance Explained
Payment security is one of the most important aspects of online checkout. Credit and debit card information is sensitive, and businesses handling card payments operate within the Payment Card Industry Data Security Standard (PCI DSS) ecosystem.
Stripe states that it is a PCI Level 1 Service Provider and describes infrastructure designed to securely store, decrypt, and transmit card information.
Businesses remain responsible for correctly configuring their websites, accounts, permissions, integrations, and operational processes.
A well-designed payment integration should also:
- Use HTTPS
- Keep website software and integrations updated
- Protect administrative accounts
- Minimize unnecessary exposure to payment information
- Validate webhook events
- Follow current Stripe security guidance
9. Fraud Prevention and Stripe Radar
Online payments naturally introduce fraud risks. Stolen card information, account takeover, automated card testing, and fraudulent purchases can result in financial losses and disputes.
Stripe Radar is Stripe’s fraud-prevention product for card payments. Stripe describes its payment infrastructure as using AI-based fraud protection and payment optimization to identify potentially suspicious transactions.
However, no automated fraud system can eliminate fraud completely. Businesses still need sensible fulfillment rules, account security, monitoring procedures, refund processes, and dispute management.
10. Stripe Refunds, Disputes, and Chargebacks
Refunds and disputes are related to payments, but they are not the same thing.
A refund is initiated by the business to return money to a customer. A dispute occurs when a cardholder challenges a transaction through the financial system, typically through their card issuer.
Businesses can help reduce avoidable disputes through:
- Clear product and service descriptions
- Recognizable billing descriptors
- Accessible customer support
- Transparent refund policies
- Delivery or fulfillment evidence
- Accurate transaction records
11. Stripe for Subscriptions, SaaS, and Memberships
Subscription businesses require more than simply charging the same card repeatedly. They may need pricing plans, billing intervals, trials, prorations, invoices, payment retries, customer self-service, and revenue reporting.
Stripe Billing is designed to manage recurring billing models and can be combined with payment collection and other Stripe services.
Common use cases include:
- SaaS businesses
- Membership organizations
- Digital services
- Subscription products
- Other recurring-revenue businesses
The correct payment architecture should always be based on the individual business model rather than a one-size-fits-all approach.
12. What Is Stripe Connect?
A traditional online business usually accepts payments for its own products or services. Platforms and marketplaces can be more complicated because money may need to move among multiple parties.
Stripe Connect is designed for platforms and marketplaces. Depending on the business model, typical use cases can include:
- Onboarding sellers or service providers
- Routing payments
- Collecting platform fees
- Managing payouts
Marketplace payment flows may also introduce additional regulatory, tax, identity, and operational responsibilities. These systems should therefore be designed carefully.
13. Can Stripe Be Used for Donations?
Stripe can be used as the payment infrastructure behind online donation experiences. Donation payment flows share many principles with ecommerce: the process should be clear, secure, mobile-friendly, and easy for the donor to complete.
Donation experiences may offer:
- Fixed donation amounts
- Custom donation amounts
- One-time donations
- Recurring donations
Organizations should also consider everything surrounding the transaction, including donor communication, receipts, recurring-contribution cancellation, data protection, accounting, tax treatment, and local fundraising rules.
The technology can process the transaction, but the organization remains responsible for the wider legal, financial, donor-management, and operational requirements.
14. Stripe and International Payments
International reach is one reason businesses consider Stripe. Stripe’s public materials describe a payments platform capable of serving customers across more than 195 countries while supporting many currencies and payment methods.
However, the ability to accept payments from customers in a country is different from the availability of Stripe accounts in that country.
International selling can also introduce additional considerations:
- Foreign exchange
- Local payment preferences
- Taxes
- Authentication requirements
- Refund procedures
- Customer support
- Country-specific legal requirements
Global payment capabilities should therefore be viewed as one part of a broader international-commerce strategy.
15. How Much Does Stripe Cost?
Stripe pricing depends on factors such as the country, payment method, Stripe product, transaction type, and in some cases a business’s negotiated agreement.
For example, at the time this guide was prepared, Stripe’s standard US pricing listed a fee of 2.9% + 30¢ per successful domestic card transaction, with additional fees applying in certain circumstances.
16. Does Stripe Replace a Bank Account?
No. Stripe should not generally be viewed as a replacement for a normal business bank account.
In a standard merchant setup, Stripe processes payment-related activity and pays eligible balances out to an external bank account according to the applicable account configuration and payout schedule.
Stripe offers additional financial products in certain markets, but availability and legal structures vary. Those products should be evaluated separately.
17. Does Stripe Build Your Online Store?
Not by itself. Stripe provides payments and financial infrastructure, but it is not primarily a complete ecommerce content-management system.
A business still needs a website, storefront, or application where products, services, content, customer accounts, and business logic are managed.
Stripe can then be integrated into custom websites, web applications, ecommerce systems, mobile apps, and other platforms.
18. Stripe APIs and Webhooks Explained
Stripe is widely known for its developer-focused APIs. An API allows software to create and manage payment-related objects and actions programmatically.
A webhook works differently. It allows Stripe to notify an application when an event occurs—for example, when a payment succeeds or a subscription changes.
Payment workflows do not always finish while a customer is still looking at the checkout page. Applications should therefore use authoritative server-side events and carefully designed state management rather than assuming that a browser redirect alone proves a payment succeeded.
19. Stripe Advantages and Trade-Offs
Potential Advantages
- Faster payment integration
- Broad payment-method support
- Developer tooling
- Prebuilt checkout options
- Recurring billing capabilities
- Fraud-prevention tools
- Large payments ecosystem
Potential Trade-Offs
- Transaction and product fees
- Dependence on a third-party provider
- Account and compliance requirements
- Development work for advanced integrations
- Country-specific availability and rules
The best payment provider is not necessarily the provider with the longest feature list. Businesses should consider total costs, target markets, customer payment preferences, subscription requirements, integration effort, support needs, payout behavior, risk profile, and long-term architecture.
20. Checklist Before Accepting Online Payments
Before launching an online payment system, work through the following checklist:
- Define exactly what you sell or collect payments for.
- Identify the countries and currencies you need to support.
- Choose payment methods based on your customers.
- Decide between hosted checkout, embedded components, or custom integration.
- Plan one-time and recurring payment flows separately.
- Test successful and failed payments.
- Test authentication requirements.
- Test refunds and cancellations.
- Verify confirmation messages and post-payment workflows.
- Secure administrator accounts.
- Keep websites and payment integrations updated.
- Understand fees and payout schedules.
- Plan dispute-handling procedures.
- Consider tax, privacy, and applicable legal obligations.
- Use test environments before accepting real customer payments.
21. Frequently Asked Questions About Stripe
Is Stripe only for large companies?
No. Stripe is used by businesses ranging from individual founders and small companies to large enterprises.
Can Stripe accept more than credit cards?
Yes. Depending on country and eligibility, Stripe supports numerous digital wallets, bank-based payment methods, buy-now-pay-later options, and other payment methods.
Can Stripe handle subscriptions?
Yes. Stripe Billing provides tools designed for recurring billing and subscription-based business models.
Can Stripe be used for donations?
Yes. Stripe can process payment flows used for one-time and recurring contributions. Organizations remain responsible for their own legal, tax, donor-management, accounting, and operational obligations.
Is Stripe secure?
Stripe provides significant payment security and compliance infrastructure. However, the security of the complete payment experience also depends on the merchant’s website, account security, integration, configuration, and operational practices.
Do I need to be a developer to use Stripe?
Not always. Prebuilt payment options can reduce coding requirements, while highly customized payment systems generally require development work.
Conclusion: What Is Stripe?
Stripe is best understood not as a single payment button, but as a broad financial infrastructure platform.
Its core purpose is to give businesses building blocks for collecting money and managing payment-related workflows without requiring them to build the underlying payments infrastructure from scratch.
For a small business, that might mean a straightforward checkout for one-time payments. For a subscription company, it may involve recurring billing and customer lifecycle management. For a marketplace, it can include onboarding users and routing funds among multiple parties.
The most important point is that payment processing is only one part of a successful customer journey. Businesses also need a clear storefront, simple checkout, appropriate payment methods, strong security, careful testing, transparent policies, and reliable post-payment communication.